
In last month’s Commercial Performance Barometer webinar, we reported on a challenging first half of the year for the sector, with signs of recovery in July and August.
Provisional data for September is also looking good, current projections suggesting a 4% rise in admissions. This will represent the third consecutive month of growth (albeit with regional variation) countering four months of decline between February and June.
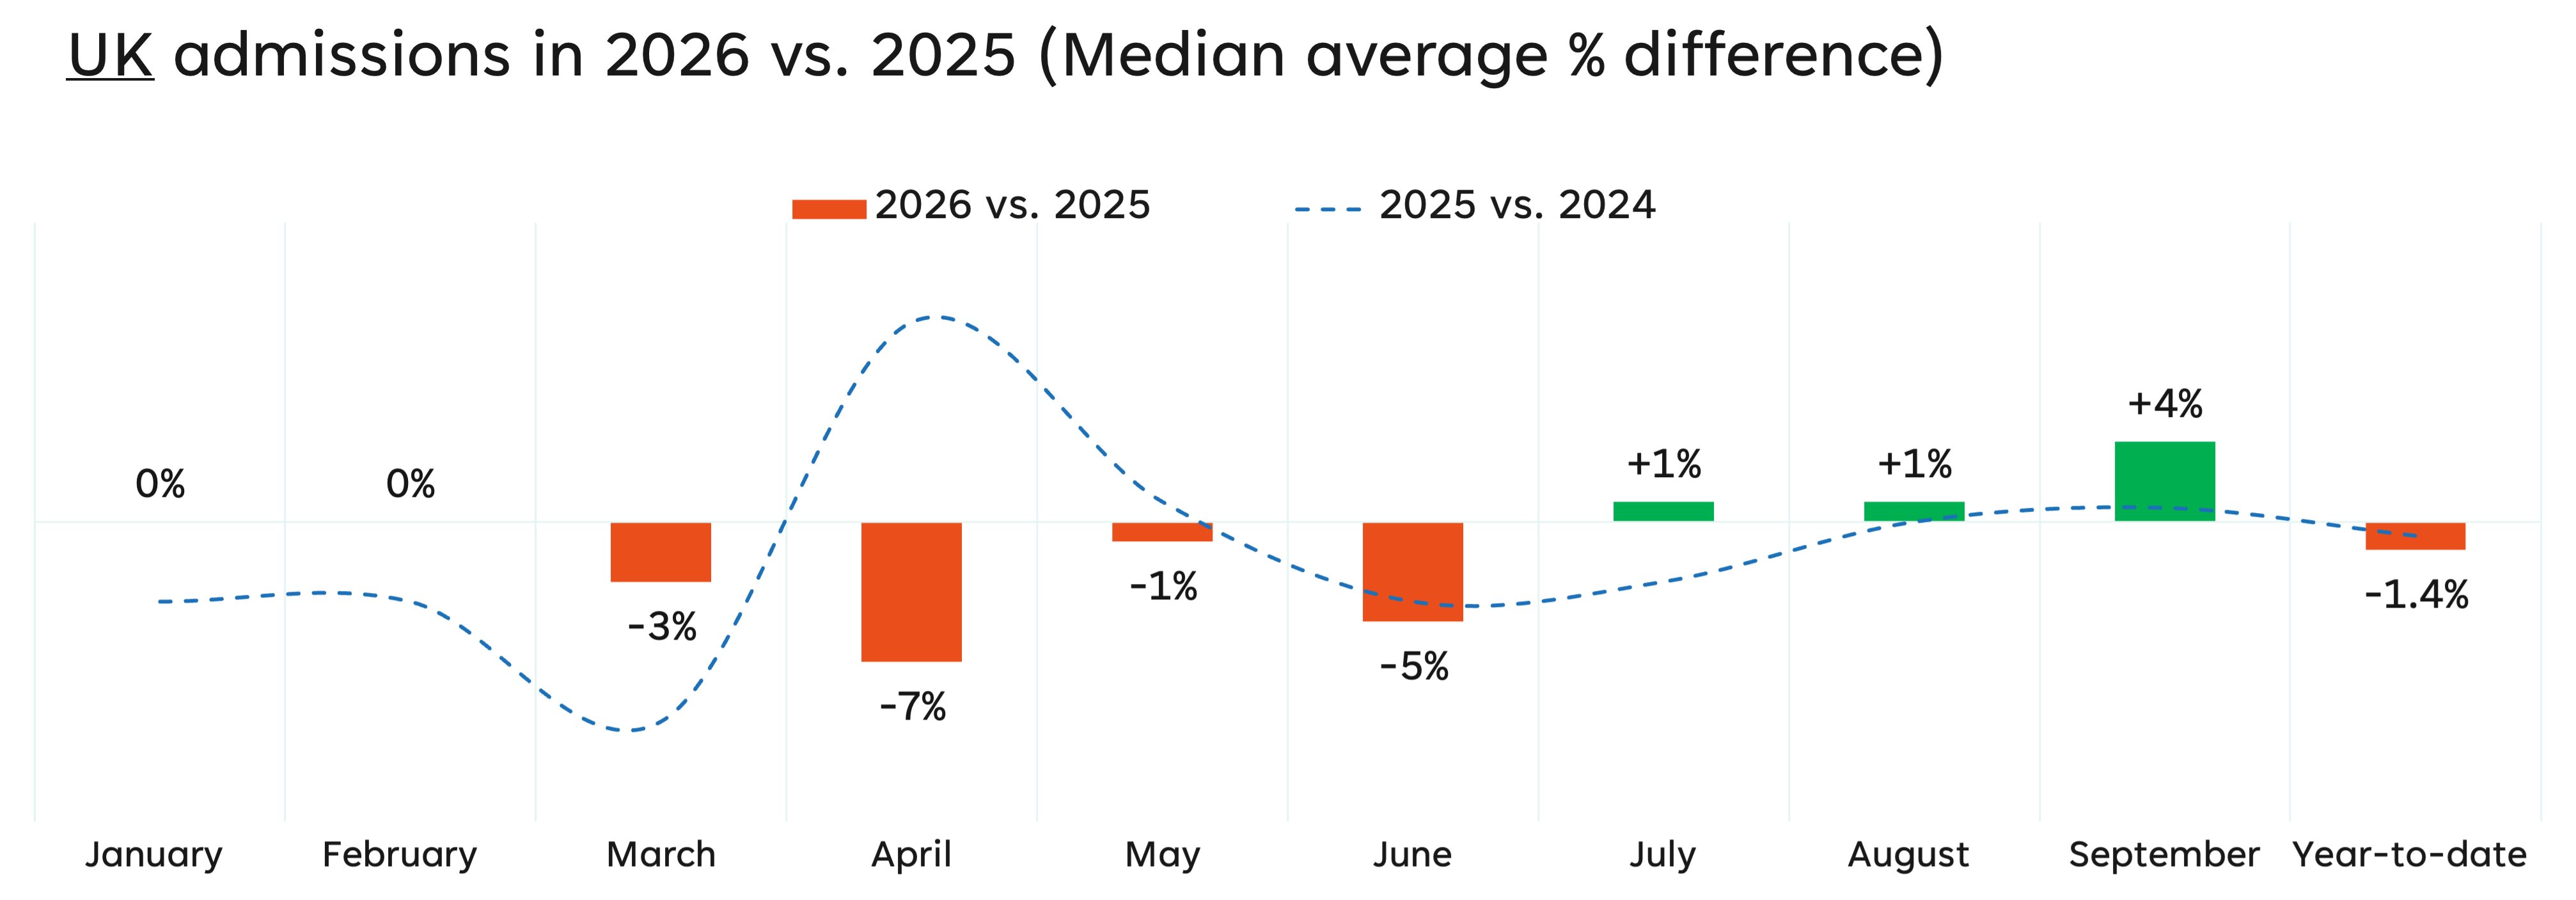
In 2025, we saw some of the strongest months in Autumn and Winter, thanks to some brilliant programming from October to December. Whilst last year’s performance will take some beating, there are signs that the cultural sector may be up to the challenge.
In last month’s webinar, we ran a snap poll to understand the sector’s planned programming for Halloween, Guy Fawkes Night and Christmas. Positively, the sector plans to increase its programming across each of these public celebrations.
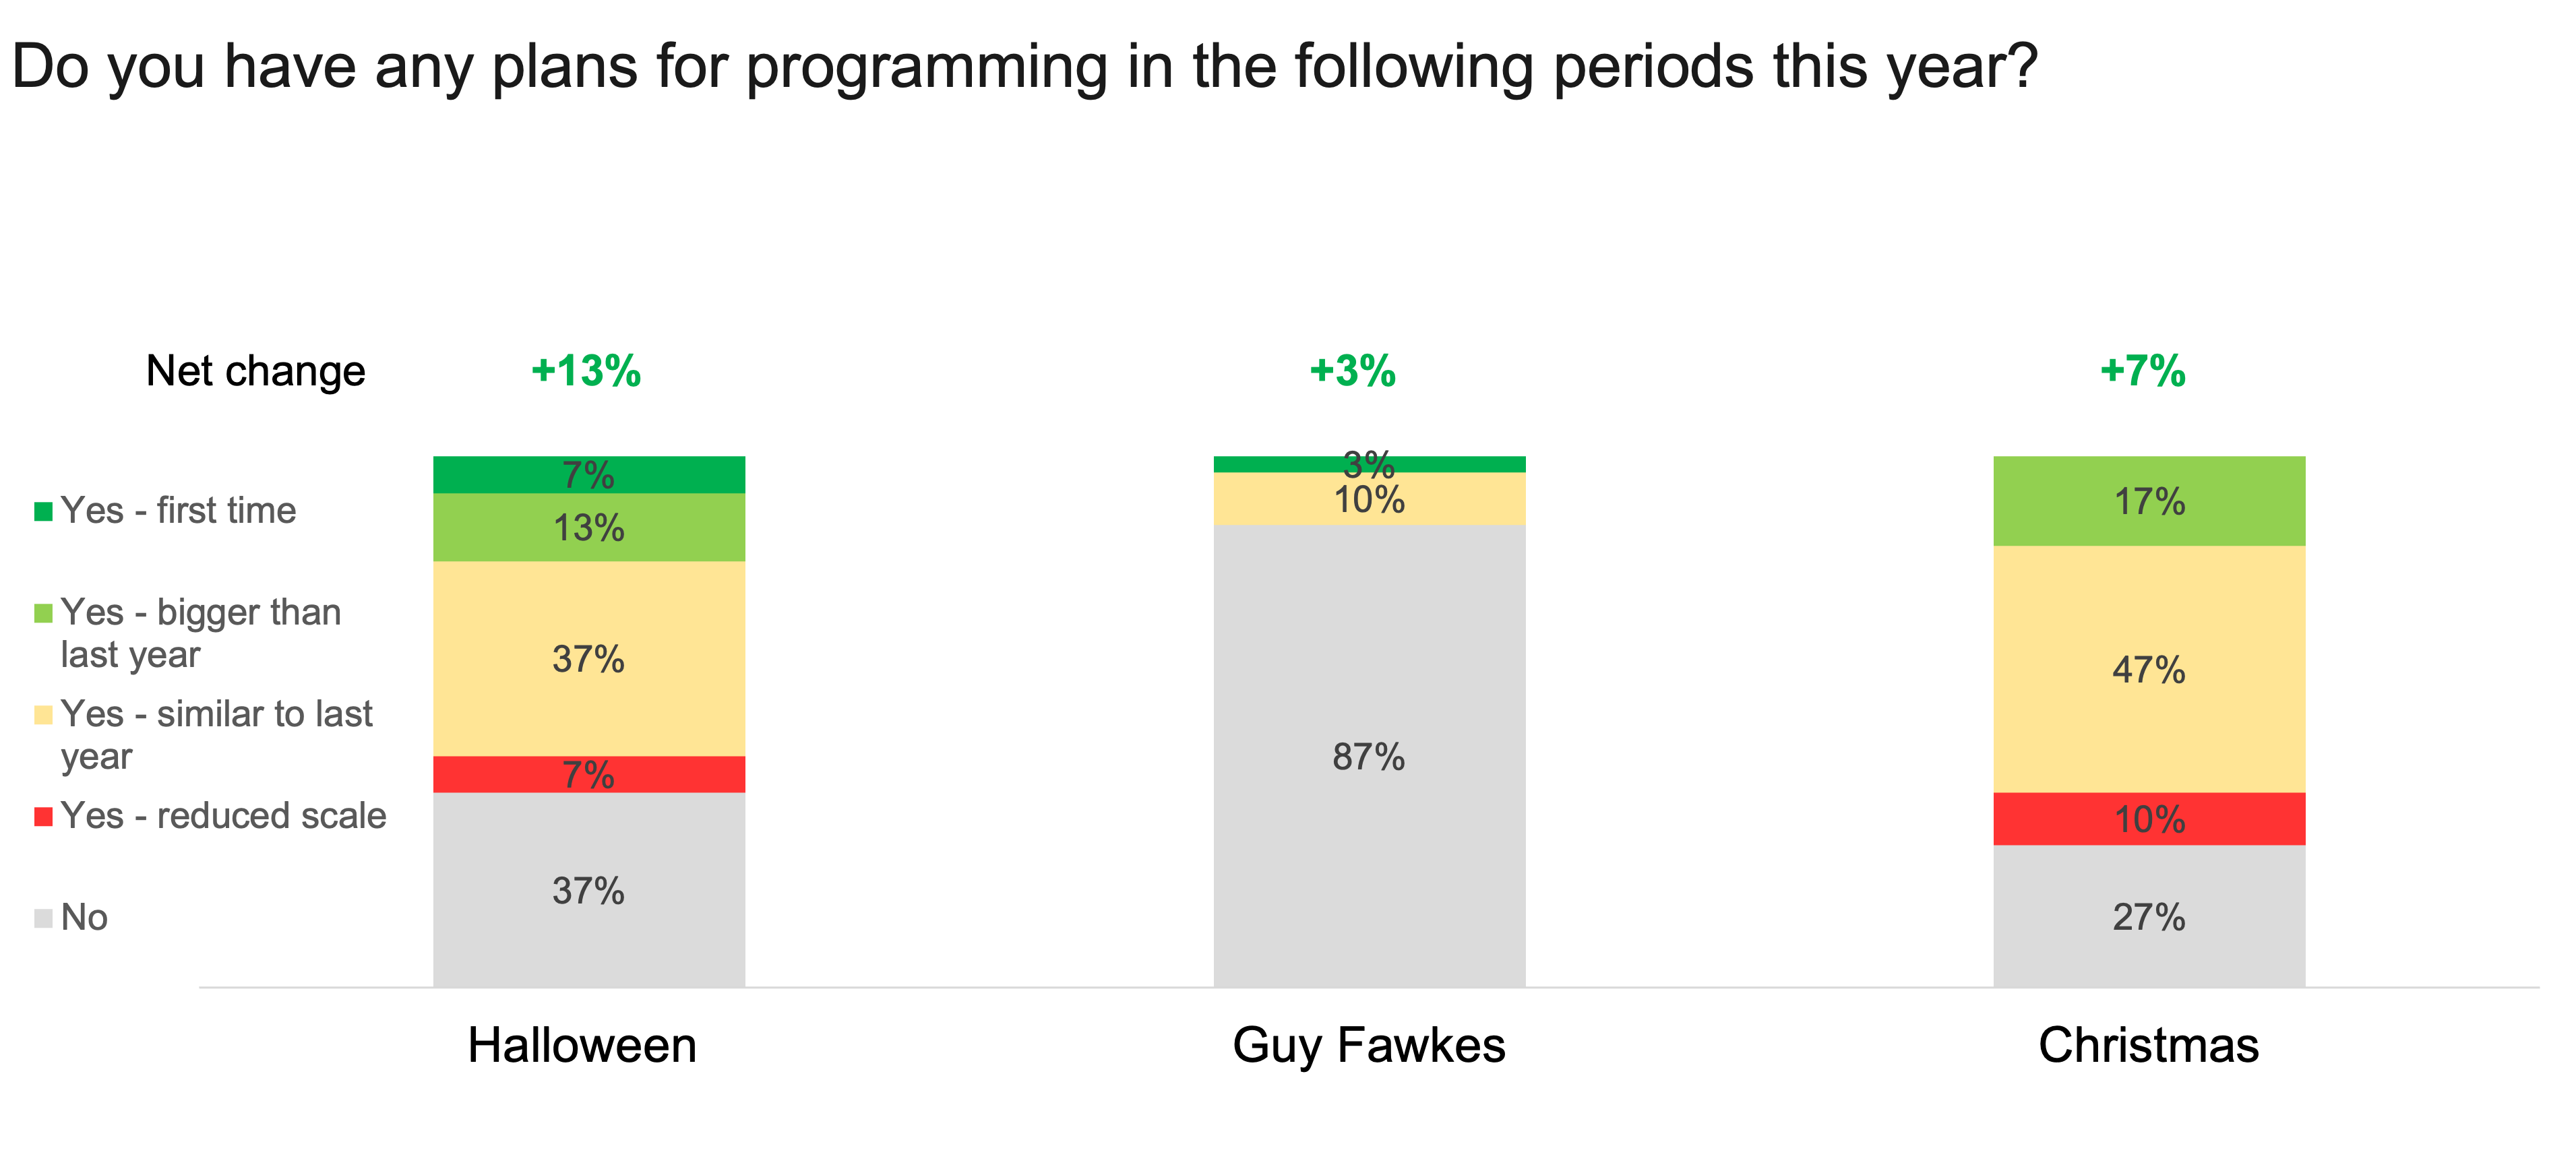
Nearly two thirds stated they are planning on Halloween programming, 7% for the first time and 13% at a bigger scale than last year (net +13% increasing the offer). Specific examples included St Albans Museum & Art Gallery’s ‘Mask Making’ workshop for families, St Fagan’s ‘Halloween Nights’, Worcester City Art Gallery & Museum’s ‘Frightful Fairytales’ sessions, and screenings of The Birds and Psycho at Cardiff Museum. It was also interesting to hear about Titanic Belfast’s preference for the seasonal over the spooky, highlighting a different route for venues that may struggle to find a relevant (and tasteful) connection to Halloween, or who are worried about market saturation.
“At Titanic Belfast we are doing an Autumn Flavours festival rather than directly related to Halloween. We do collaborations with suppliers, pop-up exhibitions, interactive exhibitions, supporting offers in our outlets, a family hay maze outside – all free.”
For Guy Fawkes the take-up was unsurprisingly lower, but it was exciting to hear about IWM Duxford’s plans to host a fireworks display on the airfield. Notably, IWM plan to keep Hangers 1 and 2 open during the display, and will hopefully attract some new enthusiast in the process. I’m sure there’ll be plenty of secondary spend too.
Unsurprisingly, programming is set to be strongest during Christmas – 3 in 4 planning something during this period. Positively, nearly 1 in 5 (17%) plan on delivering at a larger scale than in 2025 (compared to 1 in 10 at reduced scale), meaning that if demand matches supply we could be heading for another record December. Personally, I’ve already got my tickets for Christmas at Kew, but I may also head up the M25 to St Albans Museum & Art Gallery to watch ‘The Doorstep Elves’ via their Christmas Market. Titanic Belfast’s free ‘Magical Christmas Experience’ also looks like one to catch.
So in summary, a few months on from debilitating June heatwaves, there is a lot more to be happy about as we hurtle towards the festive season. Fingers crossed that the weather is kind, and people are willing to part with their pennies! We’ll keep you updated as soon as we have the numbers to share.
For more data and insights explore the Commercial Performance Barometer.
